I recently talked to a retired investor who sold one of his Multifamily buildings two years ago.
Unexpectedly, he was now facing a reduction in their overall check from Social Security, which was due to the withholding of higher Medicare premiums.
IRMAA stands for Income-Related Monthly Adjustment Amount, which is an extra surcharge added to retirees Medicare Part B and Part D premiums if their income is above a certain limit.
Retirees with high retirement income pay a larger premium for their Medicare coverage. Selling his multifamily building had given him a substantial increase in income during the year of the sale.
Because the higher premiums are calculated on a two-year lookback period, it seemed like a big surprise two years later than now he was being penalized for the year they sold this property.
HOW TO AVOID A SURPRISE
Most multifamily owners plan the sale of a building around price, timing, and 1031 options. Fewer plan around what happens to their tax return — and their Medicare bill — the year after closing.
For a retired owner, a single large, all-cash sale can do two things at once:
-
- Push years of accumulated appreciation (Cap Gains) and depreciation recapture into one tax year at the highest marginal rates available to them.
-
- Trigger a Medicare surcharge called IRMAA roughly two years later. Both are avoidable, or at least manageable, and buyers who understand this have real leverage to offer.
The Bracket Squeeze: One Big Year, Taxed at the Top
A traditional sale of an appreciated building stacks two kinds of income into a single return:
-
- Unrecaptured Section 1250 gain on the building’s depreciation (capped at 25%)
-
- Long-term capital gain on the remaining appreciation.
Even though capital gains get preferential rates, taxable income is taxable income for bracket purposes — a large sale can push a retiree who otherwise lives comfortably in the 12% or 22% bracket into paying 20% (versus 0% or 15%) on much of the gain, simply because the sale itself inflated the income used to measure the bracket.
| 2026 Long-Term Capital Gains Rate | Single Filer (Taxable Income) | Married Filing Jointly |
| 0% | Up to $49,450 | Up to $98,900 |
| 15% | $49,451 – $545,500 | $98,901 – $613,700 |
| 20% | Over $545,500 | Over $613,700 |
For a retired owner living on Social Security, a pension, and modest portfolio income, that 0% or 15% capital gains bracket is often within easy reach in a normal year. A single seven-figure closing can erase it for that one year — and, as the next section shows, for two years after that.
The IRMAA Cliff: Why the Bill Arrives Two Years Late
IRMAA — the Income-Related Monthly Adjustment Amount — is a surcharge Medicare adds to Part B and Part D premiums for beneficiaries whose Modified Adjusted Gross Income (MAGI) exceeds set thresholds.
The trap for a seller is timing: 2026 IRMAA is based on the tax return from 2024, so a large sale in 2024 or 2025 doesn’t show up as a higher Medicare bill until 2026, often after the seller has already reinvested or spent down proceeds and forgotten the sale triggered it.
It is also a true cliff, not a gradual phase-in — one dollar over a threshold can move both spouses on Medicare into a materially higher bracket, for a full year, per person.
| 2026 MAGI (Single Filer) — based on 2024 tax return | Added Part B Cost / Mo. | Added Part D Cost / Mo. |
| $109,000 or less | $0 | $0 |
| $109,001 – $137,000 | +$81.20 | +$14.50 |
| $137,001 – $171,000 | +$202.90 | +$37.50 |
| $171,001 – $205,000 | +$324.60 | +$60.40 |
| $205,001 – $500,000 | +$446.30 | +$83.30 |
| Over $500,000 | +$487.00 | +$91.00 |
Married filing jointly thresholds are roughly double the single amounts shown above. Because IRMAA is assessed per Medicare beneficiary, a married couple who are both enrolled can see this surcharge twice in the same household — and it stacks on top of the tax-bracket effect described above, all from the same closing.
Effectively, a married couple recipient can see their benefits decrease by $1,200 per month because of this income bracket shift.
The Installment Sale Alternative
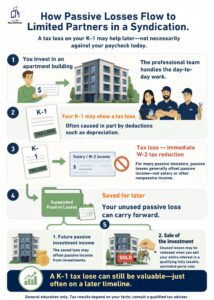
An installment sale under IRC Section 453 — the seller carries part or all of the purchase price as a note, and the buyer pays principal and interest over time — lets the seller recognize the capital gain portion of the transaction as payments are received, rather than all at once.
-
- Spreading gain across several tax years can keep the seller’s taxable income inside a lower capital gains bracket each year, and keep MAGI under the IRMAA thresholds for both current and future years, instead of spiking once and echoing into a surcharge two years later.
-
- One important limit: depreciation recapture is not deferred. (But CPAs may differ on this)
Under the installment sale rules, all depreciation recapture is taxed in the year of sale regardless of how little cash the seller actually received that year. Only the gain above recapture spreads with the note payments. For a long-held, heavily depreciated multifamily property, that recapture amount can still be significant in year one — which is exactly why this needs to be modeled with a CPA before terms are set, not after.
-
- Example: Seller Tim starts a Sales Installment agreement to sell his $1,000,000 property. He originally paid $150,000 for this property when he purchased it.
$850K of his sale is his Capital Gain- which he will pay over time with a Sales Installment.
If he totally depreciated his original $150K purchase price, then he will own depreciation recapture at potentially 25% on the $150K in the year the Installment Sale starts. So Tim will own $37,500 in recapture.
Doing a Sales Installment is able to keep Tim below the highest threshold of income for both IRMAA and the higher capital gain tax bracket, one of several real estate tax-saving strategies worth planning around, that he would fall into if he had sold his building outright.
How Buyers Can Structure the Win-Win
-
- Offer a seller an Installment Sale, letting the seller choose a payment schedule sized to stay under their target tax bracket and IRMAA threshold each year.
-
- Set interest at or above the IRS applicable federal rate so the note isn’t recharacterized under the below-market/imputed-interest rules. Currently these rates for September 2026 with annual compounding are 4.18% for short-term, 4.49% for mid-term, and 5.12% for long-term loans.
-
- Use a graduated or balloon structure — moderate annual payments with a balloon in a later year the seller chooses, so recognized gain can be timed around other income (Social Security, RMDs, other sales).
-
- Bring the seller’s CPA into deal structuring early; a buyer who proposes to model after-tax and after-Medicare outcomes signals seriousness and often earns better price or terms in return.
For buyers, this is not purely a favor — sellers who feel their tax and Medicare exposure is being taken seriously are frequently willing to accept a lower headline price, a longer close, or more flexible terms than an all-cash buyer would get.
Before You Structure Anything
Every seller’s basis, recapture exposure, other income, and Medicare enrollment status is different, and installment sale elections, related-party rules, and state tax treatment add further complexity.
This article is educational and is not tax, legal, or financial advice — any seller considering this route should work through the specifics with a CPA and, where a note is involved, an attorney experienced in seller-financed real estate.
If you’re a multifamily owner weighing a sale — you are wise to consider carefully the long term affects the sale will have on your income. When the time is right, Clear Multifamily looks forward to assisting you with the sale of your Multifamily property.